Your life.
Your Pillar 3.
Four solutions for Pillar 3 — on their own or combined. You decide how much you pay in, for how long and what for. Compare them, work out the 3a tax saving and take the one that fits you.
Goals change. Your Pillar 3 moves with you.
Pillar 3a and Pillar 3b work differently, and that is exactly why they complement each other. What is right for you depends on where you stand today and how much flexibility you need.
- Contributions deductible from taxable income
- Maximum contribution 2026: CHF 7,258 with a pension fund, CHF 36,288 without
- Capital access from 5 years before AHV age, earlier only in cases defined by law, for example buying a home
- No contribution limit
- Freely designed beneficiary structure
- Flexible capital access and adjustable savings rate
- Useful once the 3a maximum is exhausted
- Provision for partner, children or grandchildren
- Early wealth building for children or grandchildren
- Useful when saving for or insuring a loved one
Pillar 3a in particular is governed by OPP 3 (SR 831.461.3). For both pillars the cantonal tax laws also apply. The specific tax consequences depend on your canton of residence and personal situation. The information on this page is general. It does not replace tax or legal advice.
Pension provision that adapts to you. Not the other way round.
One solution for Pillar 3a, three for Pillar 3b. All fund-linked, all personally guided.
Prosperity Plus
Pillar 3b lets you tap into return opportunities and adapt your pension to fit your life.Prosperity Duo
Save for someone close to you and protect them in case you can no longer provide for them yourself.Prosperity Junior
You build wealth early for a child or grandchild. If you die, Liechtenstein Life takes over the premiums until maturity.So you know exactly what your provision can do.
Who each product is for, what applies for tax, when you can access your money and who receives what on death.¹
Comparison of the four Prosperity Pillar 3 solutions: Prosperity 3a (Pillar 3a) and Prosperity Plus, Duo and Junior (Pillar 3b).
| Category | Pillar 3aProsperity 3aDetails | Pillar 3bProsperity PlusDetails | Pillar 3bProsperity DuoDetails | Pillar 3bProsperity JuniorDetails |
|---|---|---|---|---|
| Target group | Employed people who want to build provision and save on tax | Individuals who want to save flexibly or supplement their Pillar 3a | Individuals who want to provide for someone close to them | Individuals who want to provide for a child close to them |
| Tax privileges | Premiums deductible (statutory maximum amount); payout taxable | Premiums not deductible; payout tax-free (when the statutory requirement is met) | Premiums not deductible; payout tax-free (when the statutory requirement is met) | Premiums not deductible; payout tax-free (when the statutory requirement is met) |
| Payout form at the end of the insurance term | Capital benefit (lump-sum payout) or lifelong annuity | Capital benefit (lump-sum payout) | Capital benefit (lump-sum payout) | Capital benefit (lump-sum payout) |
| Early capital withdrawal | Only in legally permitted cases, e.g. home ownership and emigration² | Possible; optional payout plan | Possible; optional payout plan | Possible; optional payout plan |
| Premiums | Periodic: from CHF 1,200 p.a.; single: from CHF 5,000 | Periodic: from CHF 1,200 p.a.; single: from CHF 10,000 | Periodic: from CHF 1,200 p.a. | Periodic: from CHF 1,200 p.a. |
| Additional payments | From CHF 50 | From CHF 500 | From CHF 500 | From CHF 500 |
| Risk protectionCover in the event of death and incapacity to work. | Death cover or premium waiver in the event of incapacity to work mandatory (combinable); incapacity annuity optional, in addition to the premium waiver³ | Death cover or premium waiver in the event of incapacity to work mandatory (combinable); incapacity annuity optional, in addition to the premium waiver³ | Death cover mandatory (premium waiver on death of the provider); premium waiver on incapacity to work of the provider optional; annuity on incapacity to work of the person close to you optional³ | Death cover mandatory (premium waiver on death of the provider); premium waiver on incapacity to work of the provider optional; annuity on incapacity to work of the child close to you optional³ |
| Beneficiary designation | On survival: policyholder; on death: statutory order⁴ | Freely determinable | The person close to you | The child close to you |
¹ This table is a simplified overview. The tariff documents and the General Insurance Conditions (AVB) of Liechtenstein Life Assurance AG prevail. As of 2026. The specific design of your policy depends on tariff, term and personal situation. The value of your investment can fluctuate; a total loss of the paid-in premiums is possible. Tax treatment in Pillar 3b depends on canton and personal situation; we recommend individual tax advice.
² The early payment of the retirement benefit is governed by OPP 3 Art. 3 ("Payment of benefits").
³ Incapacity to work: premium waiver and an annuity in the event of incapacity to work can only be selected with periodic premium payments.
⁴ For the beneficiary designation of Pillar 3a, OPP 3 Art. 2 ("Beneficiaries") applies in particular.
You don't have to decide this alone.
Over 1,000 independent intermediaries from our Swiss network are there for you, by phone or in person. Free and non-binding.
This is how much tax Pillar 3a can save.
The tax advantage comes with every 3a solution. At Prosperity the difference is how you use it. With free choice of funds and ETFs you get the most out of it, and only with the insurance solution are the premiums for your insurance cover tax-effective too.
Child deductions lower taxable income, and with it the saving.
Prefilled for cantonal capital, no church tax, adjustable. Source: FTA tax calculator, as of 2026.
Maximum 3a contribution 2026: CHF 7'258.
Estimated tax saving 2026
CHF 1'831
That's roughly CHF 153 per month.
Not a forecast, not a future value, just a model calculation for 2026.
That's the 3a maximum for this year.
Build more, stay more flexible, or provide for your family? The 3b pillar makes that possible.
See 3b pillar solutionsYour entries stay in your browser. We neither transmit nor store them. the figures and calculations in this calculator are a model calculation and constitute neither tax advice nor any tax assurance. They are a general, illustrative and simplified presentation. The actual tax treatment depends on individual circumstances. The binding assessment is made by the competent tax authority. An individual assessment requires a tax adviser. No liability is accepted for consequences arising from the use of this information. As of: tax year 2026. Full assumptions and notes
Why capital markets? Because time is the biggest lever for your money.
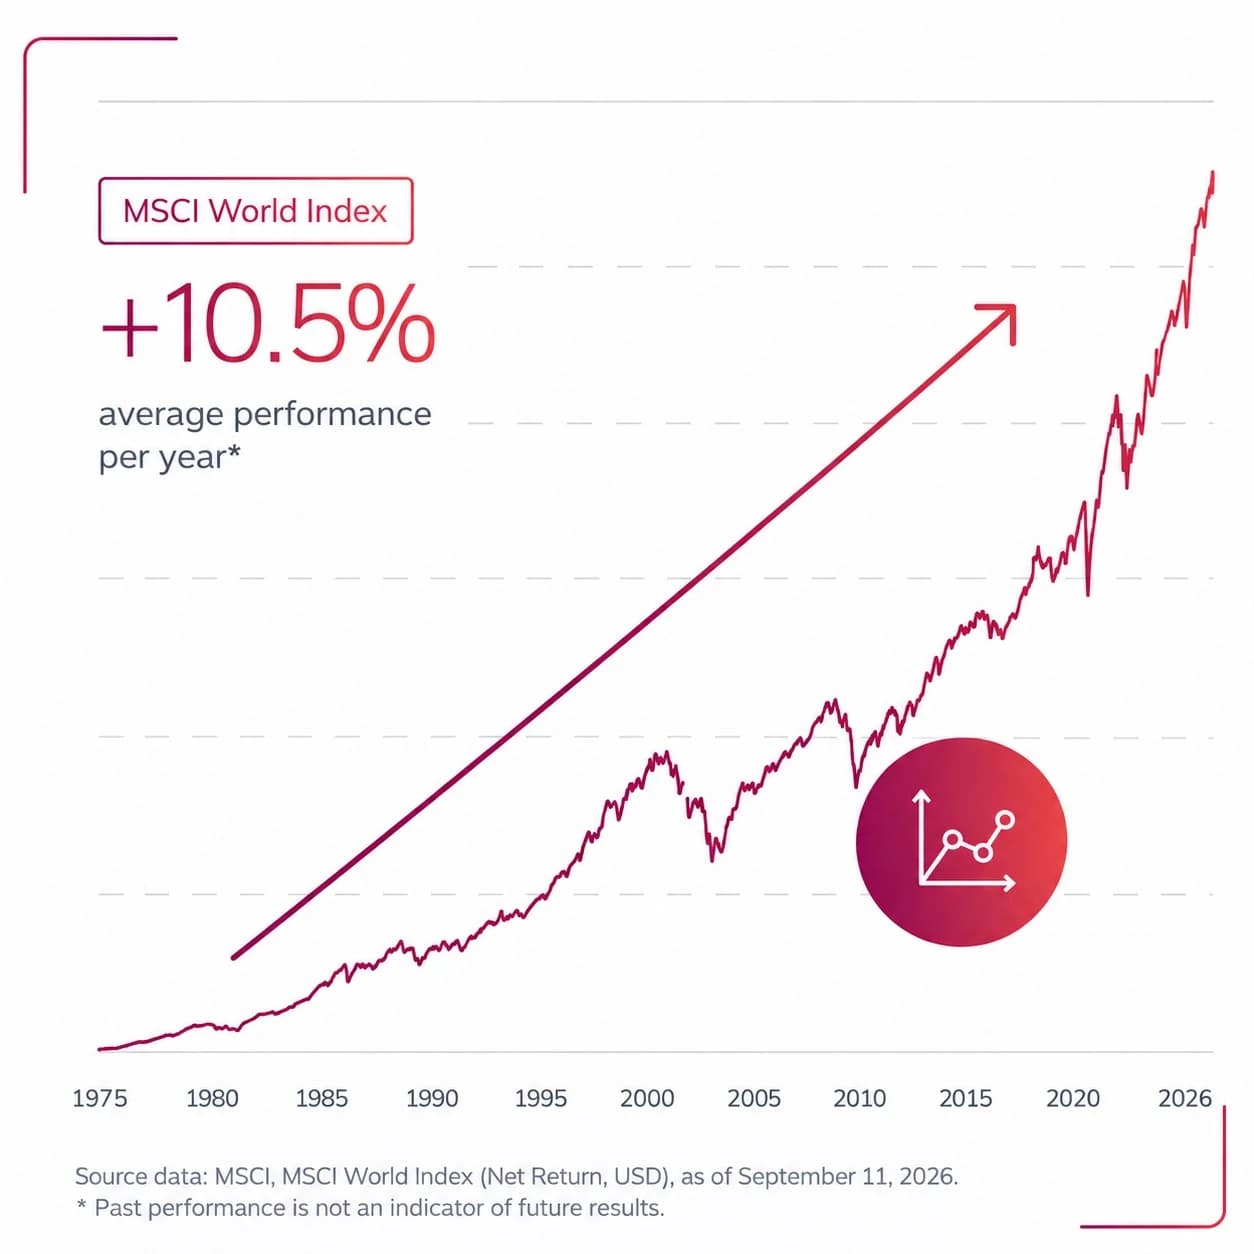
In a fund-linked policy you invest your premiums in global capital markets rather than letting them sit in a savings account. Over long horizons those markets have protected wealth against inflation and generated returns. Over 51 years the MSCI World Index returned an average of 10.5% per year (Net Return, USD, as of 11 September 2026). Volatility is part of investing. Investors who stayed the course were historically rewarded. The value of your investment may fluctuate. Past performance is not an indicator of future results.
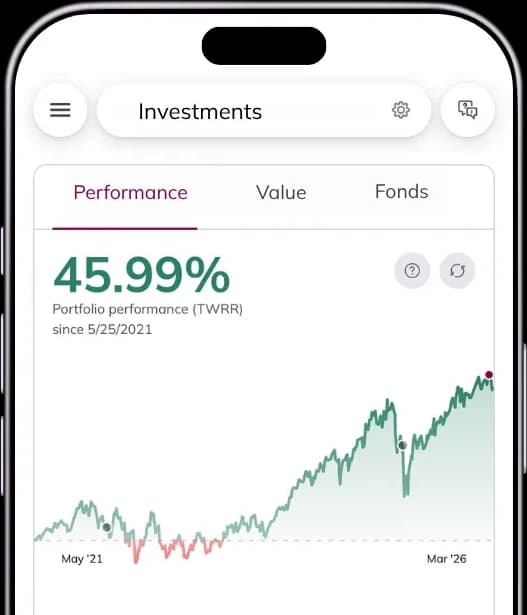
Your Pillar 3 always in your hands — with the app.
Current value, return and history since you started, without waiting for a statement.
Switch funds, make additional payments, lower, pause or raise your premium. No paperwork.
Through the app you reach your intermediary quickly and easily.
3 steps to more financial freedom.
Frequently asked questions about Pillar 3.
With a fund-linked 3a policy, you invest in funds and ETFs instead of an interest-bearing bank balance. This creates long-term return opportunities, but at the same time you also bear the risk of negative price movements.
Prosperity 3a is moreover not a pure savings solution but an insurance policy. It combines wealth accumulation with risk protection: on signing you choose either death cover or premium waiver in the event of incapacity to work (the latter only with periodic premiums). Both together is also possible. Optionally selectable are annuity payment in the event of incapacity to work, premium guarantee (50 %, 80 % or 100 %), automatic lifecycle management and rebalancing.
The value of your investment can fluctuate. Past performance is not an indicator of future results. A cancellation deduction applies on early surrender. The exact conditions are set out in the General Insurance Conditions, which we provide before the contract is concluded.
Pillar 3a is state-encouraged private pension provision: contributions can be deducted from taxable income. In return, payout and use are regulated by law. Pillar 3b is free private pension provision. It offers more flexibility on contributions, term and payout, but its contributions are not tax-deductible. Because of these structural differences, the two pillars complement each other well. The differences are set out row by row in the comparison table further up.
Within a fund-linked policy, under current Swiss tax law no ongoing income tax is generally levied on the investment income. Switching between funds usually does not trigger income tax. Only the surrender value of a Pillar 3b policy is subject to annual wealth tax. Pillar 3a assets are exempt from wealth tax until they are paid out. Payouts from free pension provision (Pillar 3b) are exempt from income tax provided the statutory conditions are met.
Maximum Pillar 3a deductions (2026) (linked to BVG threshold values, subject to official adjustment):
- Employed persons with a pension fund: CHF 7,258
- Employed persons without a pension fund: CHF 36,288 (20 % of net earned income)
The 3a tax calculator shows how much tax a 3a contribution can save. Pillar 3a in particular is governed by BVV 3, Ordinance on Tax Deductibility of Contributions to Recognised Forms of Pension Provision (SR 831.461.3); further federal and cantonal tax provisions also apply.
This section is general information and does not replace tax or legal advice. Amounts and rules can change. The actual tax effects depend on your canton of residence and your individual situation.
Pillar 3a provides for an early withdrawal in certain life situations, e.g.:
- Emigration: On permanently leaving Switzerland, a surrender of the policy is possible. You are obliged to report a change of residence within 30 days. The tax treatment of the withdrawal differs between EU/EFTA and third countries.
- Self-employment: On taking up full-time self-employed activity and discontinuing mandatory occupational provision, a surrender is permitted. The written consent of your spouse or registered partner is required.
- Home ownership purchase: A full advance withdrawal or a partial surrender every five years is possible for owner-occupied residential property. With the privileged advance withdrawal, the cancellation deduction is waived and the loyalty fund is paid out in full. Here too, the written consent of your spouse or registered partner is required. In the case of a partial surrender, the remaining value of the investment assets must amount to at least CHF 500.
Pillar 3a is governed in particular by the Ordinance on the Tax Deductibility of Contributions to Recognised Pension Schemes (OPP 3) as well as the cantonal tax laws. For the specific assessment of your situation, we recommend consulting a tax adviser or a lawyer.
You can in principle have your existing 3a balance transferred into a Prosperity 3a policy. A direct transfer from one recognised 3a solution to another does not count as a payout and as a rule triggers no income tax. The transferred legacy amount itself is not a new deductible premium. You do, however, keep the deductibility of the premiums paid in the current year, up to the maximum amount.
Additionally: Premium gaps from previous years (from tax year 2025) can be made up through retrospective buy-ins.
How the switch works: Your intermediary guides the switch and coordinates the next steps with your previous provider. Usually the details of the existing 3a solution and a signed transfer or dissolution declaration are required for this. A switch ideally before year-end secures the tax advantage for the current year.
What you should know for context: When switching to the insurance policy, a risk assessment is carried out which can result in risk surcharges or coverage exclusions. If you choose the Premium Guarantee Select, a minimum insurance term of 20 years (Select 50/80) or 30 years (Select 100) applies.
Costs consist of the fund-linked policy's acquisition and administration fees, the fund costs (TER) of the funds you select, and the costs of the included risk cover and guarantees.
You receive a full cost overview in the conversation with an intermediary. The offer states the costs as a percentage reduction in return. The actual amount depends on the product, its configuration and your situation.
Yes. You choose freely from over 180 funds and ETFs, and within our fund-linked policies you can adjust your investment strategy on an ongoing basis. Fund shift (rebalancing existing amounts) and fund switch (changing the allocation of future contributions) are usually free of charge up to twelve times a year. These changes remain tax-neutral inside the policy.