The invisible pension gap for women
Why brokers should look beyond the obvious
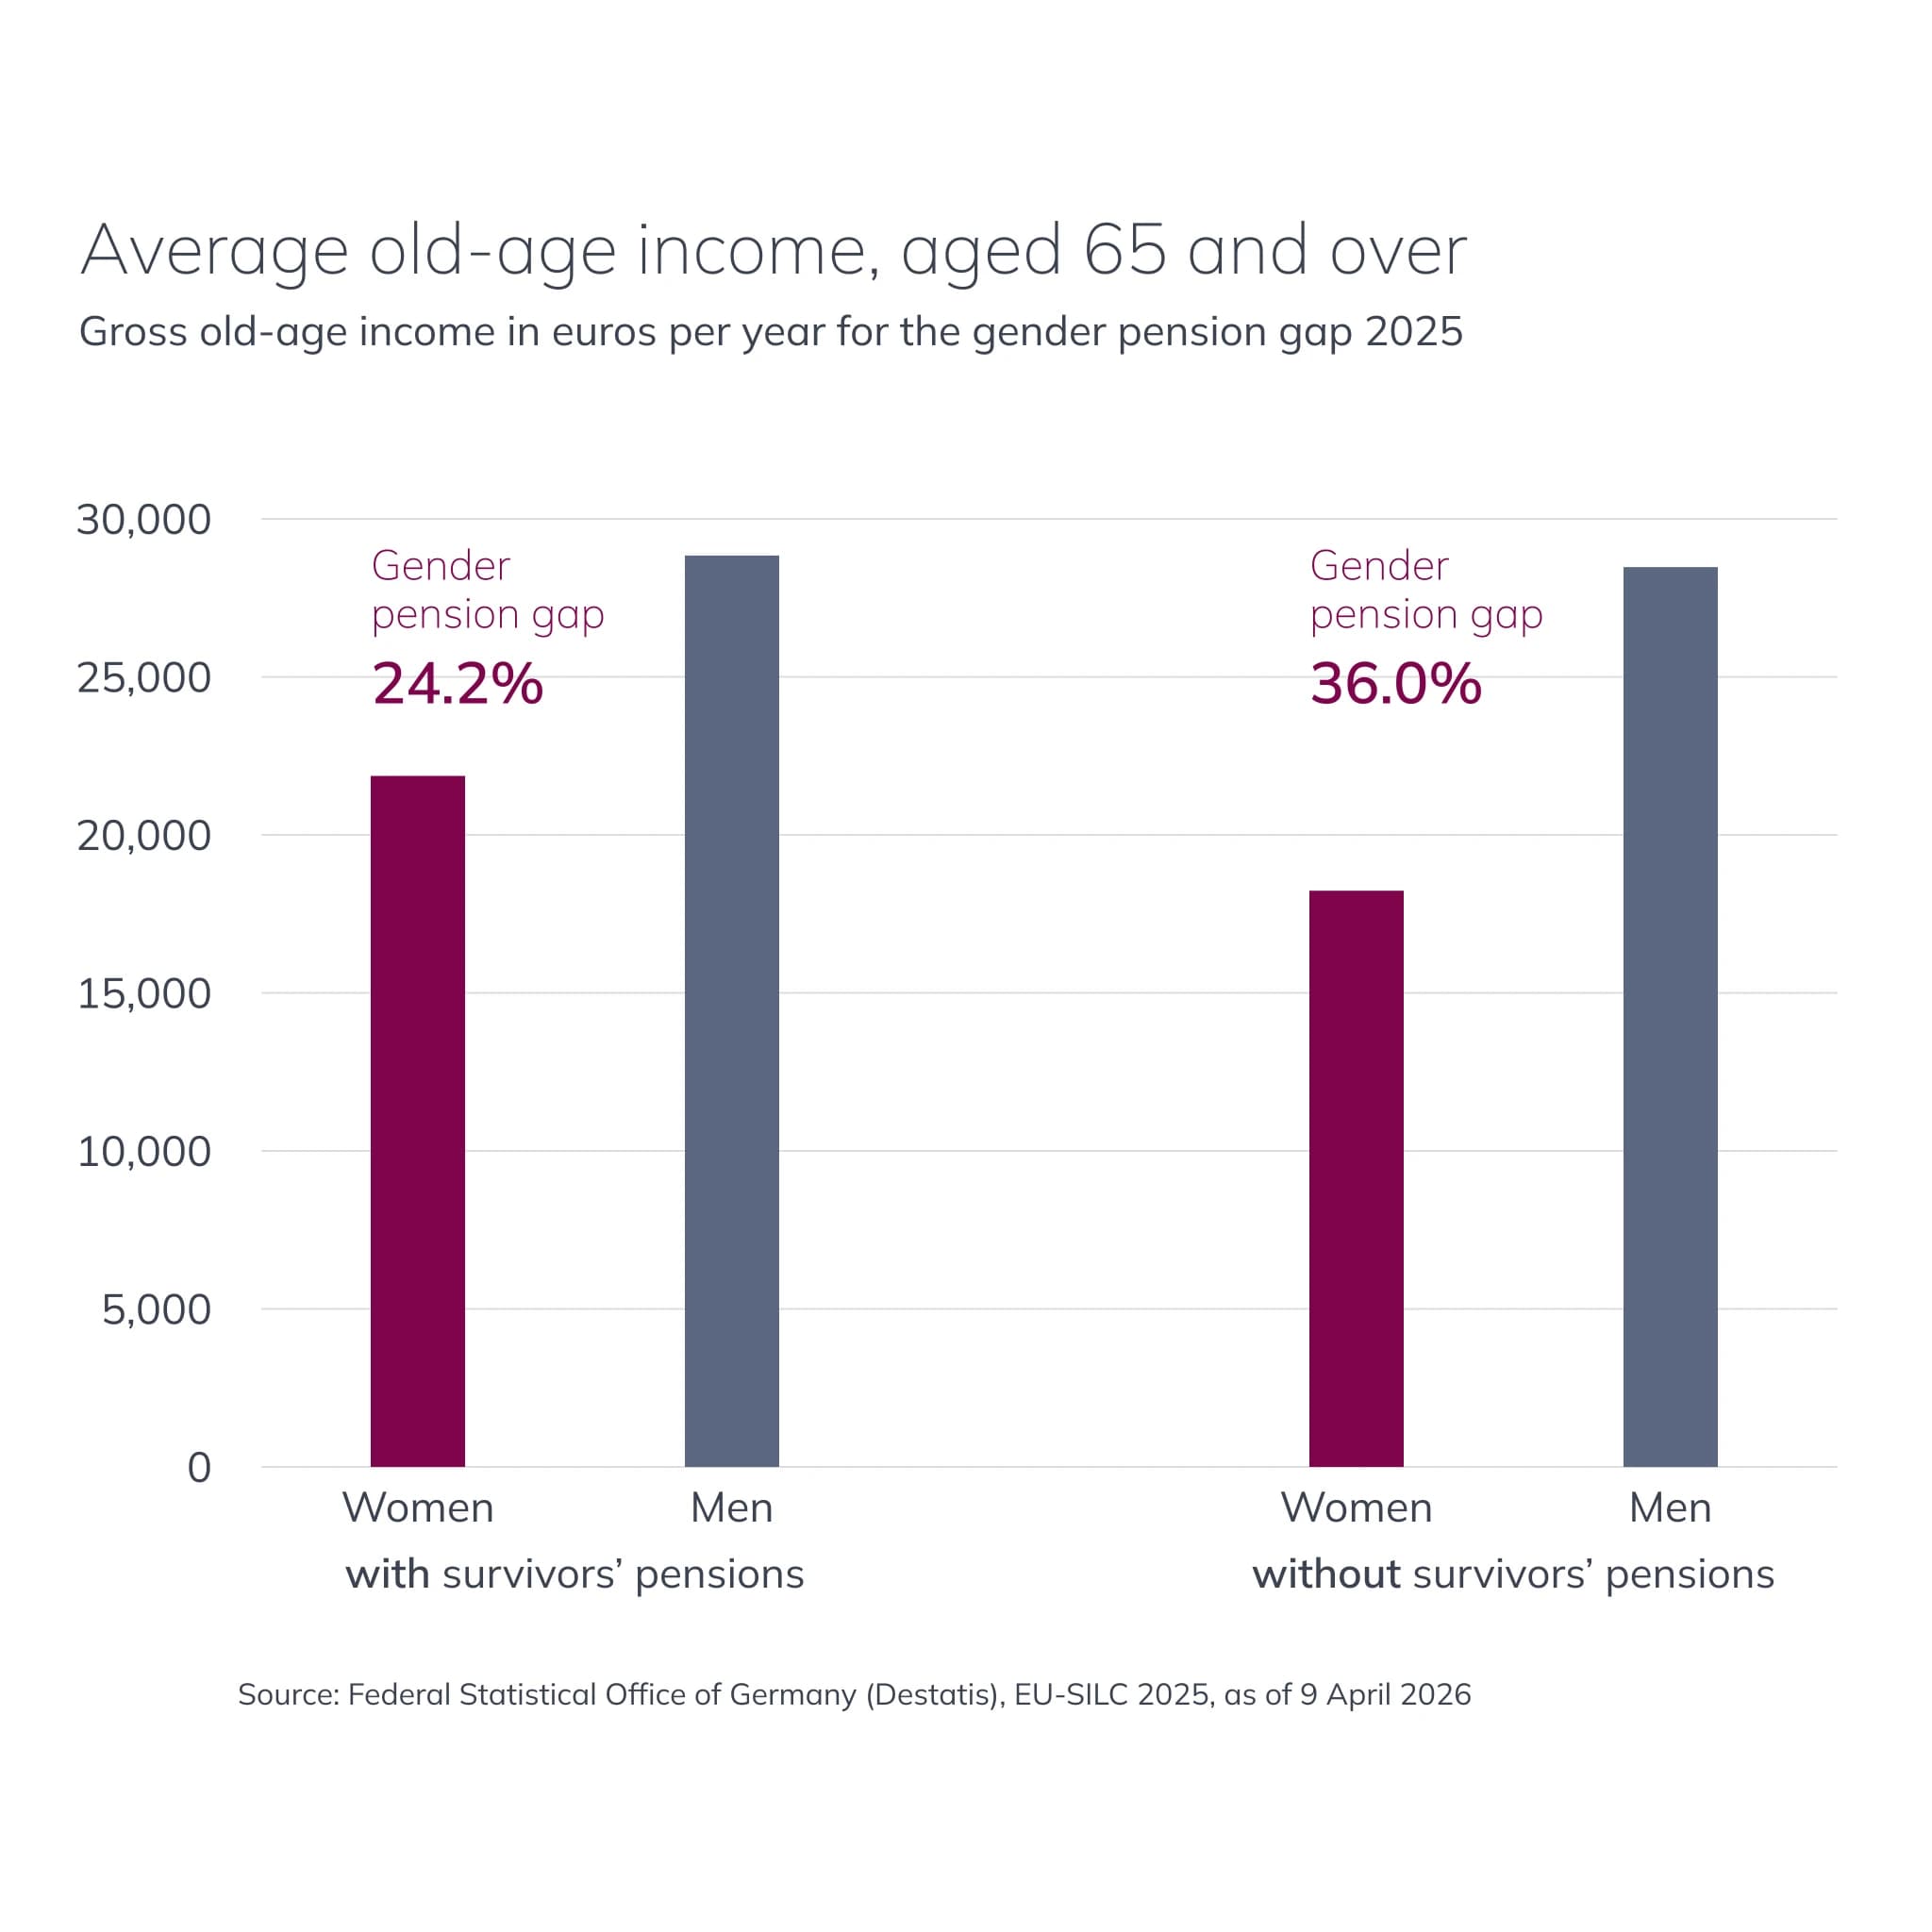
The fact is that in retirement, women often have significantly lower pension entitlements than men. According to the Federal Statistical Office (Destatis), the gender pension gap in Germany most recently (2025) stood at 36.0%, measured by own retirement income without survivors' pensions. That means women aged 65 and over received an average of around €1,520 gross a month, while men received around €2,370, a difference of around €850 a month. This pension gap often remains invisible, and its impact is vastly underestimated. The consequences are serious, not only for the women affected but for society as a whole.
The scale of the pension gap
Women often have no clear idea of how large their pension gap actually is. According to a study by the German Institute for Economic Research (DIW Berlin), the so-called motherhood pension gap in western Germany is 27%: at age 60, mothers born between 1952 and 1959 had pension entitlements more than a quarter lower than those of childless women (DIW Weekly Report 12+13/2025). Every missed opportunity for pension advice makes the problem worse and leaves valuable new-client potential untapped.
Women are financially disadvantaged in old age for many reasons:
- Career breaks: pregnancy, parental leave and caring for relatives lead to lost earnings and lower pension entitlements.
- Part-time work: around 49% of working women work part-time, compared with only 12% of men (Destatis). This reduces their income and pension contributions.
- Gender pay gap: on average, women earn around 16% less than men (Destatis, unadjusted gender pay gap 2025), and the difference is considerable even in comparable positions.
- Lack of financial literacy: without enough knowledge of financial products and retirement planning, important decisions are postponed or avoided.
- Reservations about pension products: many women hesitate to tie up larger sums for the long term, for fear of financial constraints or a lack of flexibility.
The untapped potential for brokers
This is an opportunity for brokers who look beyond the obvious:
- Actively involve the partner: in the advisory meeting, ask about the financial situation of the client's wife or partner. Offer to include her in future meetings.
- Inform and raise awareness: explain the specific risks and pension gaps that affect women. Knowledge motivates action.
- Tailored solutions: offer individual pension concepts designed around women's needs, with flexibility and security.
Your role as an intermediary: empathy and foresight Engage actively with your clients' life situations to recognise their individual needs. Holistic advice strengthens the client relationship and sets you apart from competitors.
Conclusion The pension gap for women is not just a social problem. It is also a missed opportunity for brokers and intermediaries. Use it to position yourself as a trusted partner for the whole family. Proactive, comprehensive advice builds long-term client loyalty and helps reduce financial inequality. At the same time, you grow your client portfolio.
Article published by Prosperity Solutions AG
More topics to deepen your knowledge:


