Altersvorsorgedepot
Germany's state-subsidised Riester successor from 2027, the base of your provision. Invest subsidised in funds and ETFs and, step by step, combine it into a plan that fits your life.

Comprehensive provision is built from many blocks
The subsidised Altersvorsorgedepot is a solid foundation. Only at Liechtenstein Life do you combine it with our other solution modules: Invest flexibly builds wealth with no upper limit, Pension provides stable protection with an additional tax advantage, and Wealth enables succession planning. The strength lies above all in the combination.
Altersvorsorgedepot calculator:
how much subsidy the state adds
Set your contribution, children and age. You'll see instantly how much the state adds and how the capital could grow until retirement.
Annual figures, shown for a year at full child-benefit entitlement. The child allowance applies in every year child benefit is received for the child. The total capital counts it across all entitled years.
The figures and calculations in this calculator are a model calculation and constitute neither tax advice nor any assurance under tax law. They are a general, illustrative and simplified presentation. The actual tax treatment depends on personal circumstances. The binding assessment is made by the competent tax authority. An individual assessment needs a tax adviser. No liability is accepted for consequences arising from the use of this information. The expected return is an assumption, not a guaranteed value. Capital markets carry the risk of fluctuation and loss. Our exact product costs are not yet fixed. For illustration we assume 1% effective costs per year, the legally defined cap for the standard depot. As of August 2026. All assumptions and legal notices
What our Altersvorsorgedepot offers
- 50% subsidy on the first €360 and 25% on the next €1,440. That gives up to €540 base allowance per year.
- Child allowance: up to €300 per child per year.
- Career-starter bonus: a one-off €200 for under-25s.
- Invest subsidised in funds and ETFs.
- Use return potential over the whole term.
- Taxed only at payout, from 65, so your capital stays invested and has more time to grow.
- Many self-employed become directly eligible for the first time.
- No statutory-pension-insurance membership required.
- Including compulsory members of professional pension schemes.
- Up to 30% of the capital as a one-off partial lump-sum payout at the start of the payout phase.
- Then either a lifelong annuity that protects you especially in very old age.
- Or a payout plan that keeps your capital invested.
Your pension, always to hand
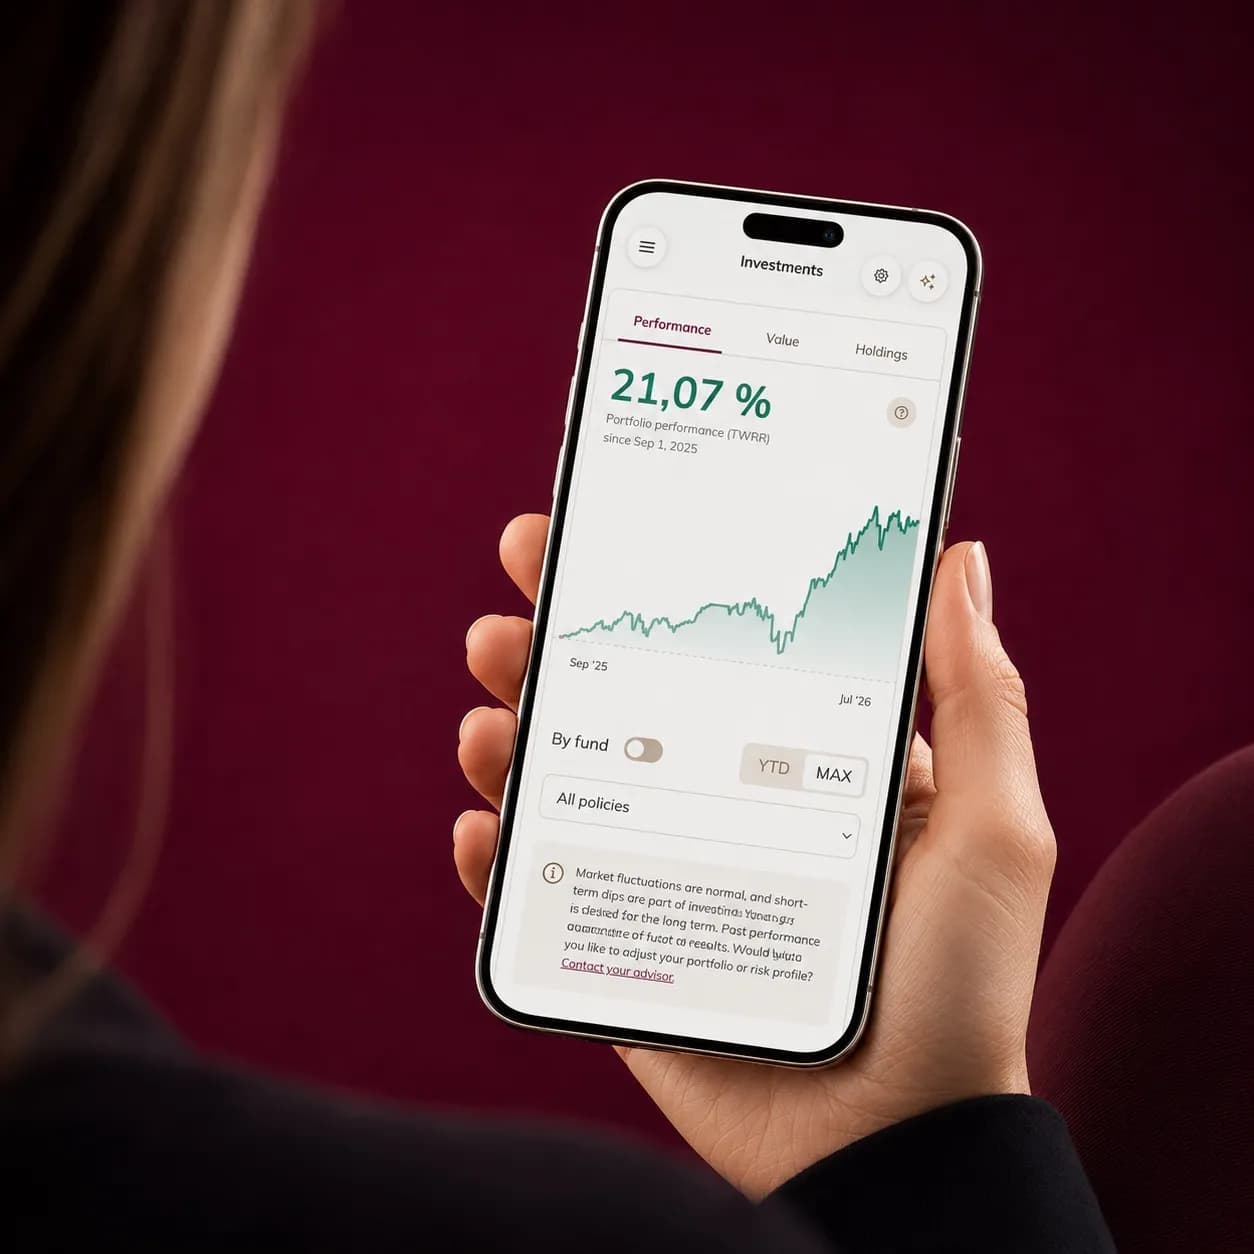
You manage your Altersvorsorgedepot entirely in our app: clear and with you whenever you like.
Track contributions, subsidy and each fund's performance whenever you like.
From setup to changes, everything runs digitally.
Adjust contributions and more, right in the app.
Start fresh or bring your Riester
Don't have an intermediary yet?
Independent intermediaries from our network inform you personally about the Altersvorsorgedepot and set up the pre-registration for you. Free of charge and without obligation.
Frequently asked questions about the Altersvorsorgedepot
The Altersvorsorgedepot is a new form of state-subsidised private pension provision in Germany. It was introduced by the pension reform act and is set to be offered from 1 January 2027 by providers of certified retirement contracts.
Unlike classic Riester products, guarantees can be waived. This enables a more return-oriented investment, for example via funds and ETFs. However, not just any investment qualifies. Only products that meet the statutory requirements and are certified.
For new contracts from 2027 the new product world replaces the previous Riester system. Existing Riester contracts remain protected, however, and can generally be continued. Liechtenstein Life is preparing the Altersvorsorgedepot for launch from 2027. Ours is the Altersvorsorgedepot with a free choice of funds.
Both are Altersvorsorgedepots. The difference lies in how freely the investment is configured, and in what the contract may cost at most.
The subsidy, the allowances, the taxation and the payout rules are the same. Three things differ:
- The fund selection. In a standard depot the provider fixes two funds, one return-oriented and one lower-risk. In an Altersvorsorgedepot without presets you choose yourself.
- The shifting. In a standard depot your balance moves step by step into the lower-risk fund in the years before the payout, unless you object.
- The costs. In a standard depot effective costs are capped by law at 1.0%. That figure covers every cost of the contract.
That does not make the standard depot the safe option. The value of your investment can go down as well as up, and there is no contribution guarantee. The presets take the fund selection off your hands, not the investment risk.
We expect to offer both from 1 January 2027. At the centre is the Altersvorsorgedepot with a free choice of funds, where you choose the funds yourself.
Source: BMF FAQ on the standard depot.
The Altersvorsorgedepot mainly suits people who save for retirement over the long term and want to use the return potential of funds and ETFs. The longer the period until retirement, the more capital-market growth and compounding can work in your favour, and the easier it is to ride out interim fluctuations.
It is especially relevant for many self-employed, who unlike with Riester are directly eligible for the first time, for families with children (child allowance) and for career starters under 25 (one-off bonus). Anyone who already holds a Riester contract and wants to switch into a more return-oriented framework can also benefit. If you value flexibility, you can choose between a lifelong annuity and a payout plan, with up to 30% as a lump sum at the start of the payout phase.
People who have only a few years left until retirement should check carefully, because there is then little time to ride out price fluctuations. Whether the Altersvorsorgedepot is worthwhile in your situation is shown by the subsidy calculator.
Sources: BMF FAQ on eligibility and payout options. General information, not investment advice.
On the first €360 of own contributions per year there is a base allowance of 50%. On further contributions up to a total of €1,800 per year there is a 25% allowance. This gives a maximum base allowance of €540 per year.
For children there can additionally be a child allowance: 100% of contributions up to €300 per child per year, provided child benefit is granted for the child. Anyone not yet 25 at the start of the contribution year also receives a one-off €200 career-starter bonus.
In the payout phase, subsidised benefits are taxed on a deferred basis at your individual rate. How much adds up in your situation is shown by the subsidy calculator.
Sources: BMF FAQ on the tax subsidy. Bundestag on the Finance Committee amendments. General information, not tax advice.
Yes, the circle of eligible people is being widened. In future, many self-employed people are also directly eligible, in particular self-employed individuals with income under § 15 EStG or § 18 (1) nos. 1–3 EStG who have filed a tax return. Compulsory members of professional pension schemes are also included.
So the statement "the self-employed are eligible" should not be taken too broadly: many self-employed people become directly eligible for the first time, but actual eligibility depends on the type of income and personal circumstances. For higher, tax-deductible contributions, the Basisrente (Rürup) can be a complementary option.
Source: BMF FAQ on eligibility.
As subsidised retirement provision, the Altersvorsorgedepot is earmarked. In principle the benefits are meant to flow only in the payout phase, as a retirement benefit or via a long-running payout plan.
The earliest possible start of the payout phase is generally on reaching age 65. An earlier start may be possible in certain legally defined cases, for example if a statutory pension or comparable provision is already being paid before 65.
Early withdrawals are subsidy-neutral only in certain cases, e.g. via home-ownership pension support, a partial lump-sum payout of up to 30% at the start of the payout phase, or the commutation of a small pension. If subsidised assets are used outside the permitted rules, this is a harmful use. The allowances and any tax benefits attributable to it must then be repaid. If you want to keep part flexibly available, combine the subsidised Altersvorsorgedepot with a further solution such as Liechtenstein Life Invest.
The German Bundestag passed the private pension reform on 27 March 2026. According to the Federal Ministry of Finance, saving can begin from 1 January 2027.
Ours is the Altersvorsorgedepot with a free choice of funds.
The key rules of the reform are set by law. We are preparing our offering, and you can today.
Do you have an intermediary? They can already set up a pre-registration for your Altersvorsorgedepot today, and you can sign straight away on 1 January 2027.
Yes, in two ways: on the waiting list or with a pre-registration.
- Waiting list. You add yourself to the and are the first to know when it starts. If you already have an intermediary with us, they see your entry and can get in touch.
- Pre-registration. Your intermediary records the details for your Altersvorsorgedepot with you. The pre-registration is neither an application nor a contract. It stays non-binding and editable, and you see it in the app, after an invitation once you have accepted it. You can then sign straight away on 1 January 2027, and if you are eligible, your contributions are subsidised from the first month.
The Altersvorsorgedepot is the subsidised foundation. Its full effect comes in combination with our other solutions, at Liechtenstein Life from a single source. This offer is available in this form from us.
- Liechtenstein Life Invest builds wealth with no upper limit in funds and ETFs, flexibly available. The sensible add-on once you want to save beyond the subsidised €1,800/year, for the part the subsidised Altersvorsorgedepot no longer covers.
- Liechtenstein Life Pension is the Basisrente (Rürup): higher contributions are tax-deductible. Ideal for the self-employed and high earners who want to save tax on top of the Altersvorsorgedepot.
- Liechtenstein Life Wealth transfers wealth tax-efficiently and plans your succession. The solution for when your provision is in place and it's about the next generation.
The value of your investment can go down as well as up. Which combination suits you is shown in the solutions.
As of September 2026. The Altersvorsorgedepot launches on 1 January 2027. Individual conditions (incl. cost cap, transfer modalities) will be finalised via implementing regulations. Figures are therefore subject to the final regulation. All investments are capital-market-dependent. Values can rise or fall and capital loss is possible. General information, not investment, tax or legal advice. Sources: BMF FAQ on the reform of private pension provision, Bundestag resolution of 27 March 2026, Federal Government.